The True Cost of Borrowing: Beyond the Interest Rate
Taking a loan is one of the biggest financial commitments you'll ever make. Whether it's for your dream home, a new car, or personal needs, the 'EMI' (Equated Monthly Installment) is the number that dictates your monthly budget. But do you know how that monthly number is determined?
Many borrowers make the mistake of looking only at the headline interest rate. However, loan tenure and the compounding frequency significantly alter the total interest you pay back over time.
How to Calculate EMI Manually: The Mathematical Formula with a Real Example
If you want to know how to calculate EMI manually on paper or in a spreadsheet, here is the universal formula used by banks and financial institutions:
EMI = [P × r × (1+r)n] / [(1+r)n – 1]
Where:
- P (Principal): The total loan amount borrowed (e.g., ₹10,00,000).
- r (Monthly Interest Rate): The annual rate divided by 12 months, then divided by 100. If your annual rate is 12%,
r = 12 / (12 × 100) = 0.01. - n (Tenure): The total number of monthly payments. For a 5-year loan,
n = 5 × 12 = 60 months.
Step-by-Step Manual Calculation Example:
Let's calculate the manual EMI for a ₹1,00,000 personal loan at an annual interest rate of 12% for a duration of 1 year (12 months):
- Step 1: Convert annual rate to monthly rate (r):
r = 12% ÷ 12 = 1% per month = 0.01 - Step 2: Calculate the compounding factor (1+r)n:
(1 + 0.01)12 = (1.01)12 ≈ 1.126825 - Step 3: Calculate the numerator [P × r × (1+r)n]:
1,00,000 × 0.01 × 1.126825 = ₹1,126.825 - Step 4: Calculate the denominator [(1+r)n – 1]:
1.126825 – 1 = 0.126825 - Step 5: Divide the numerator by the denominator:
EMI = 1,126.825 / 0.126825 ≈ ₹8,884.88 per month (rounded to ₹8,885)
Over 12 months, you will pay 12 × ₹8,885 = ₹1,06,620. Your total interest paid is ₹6,620.
How Reducing Balance Amortization Works
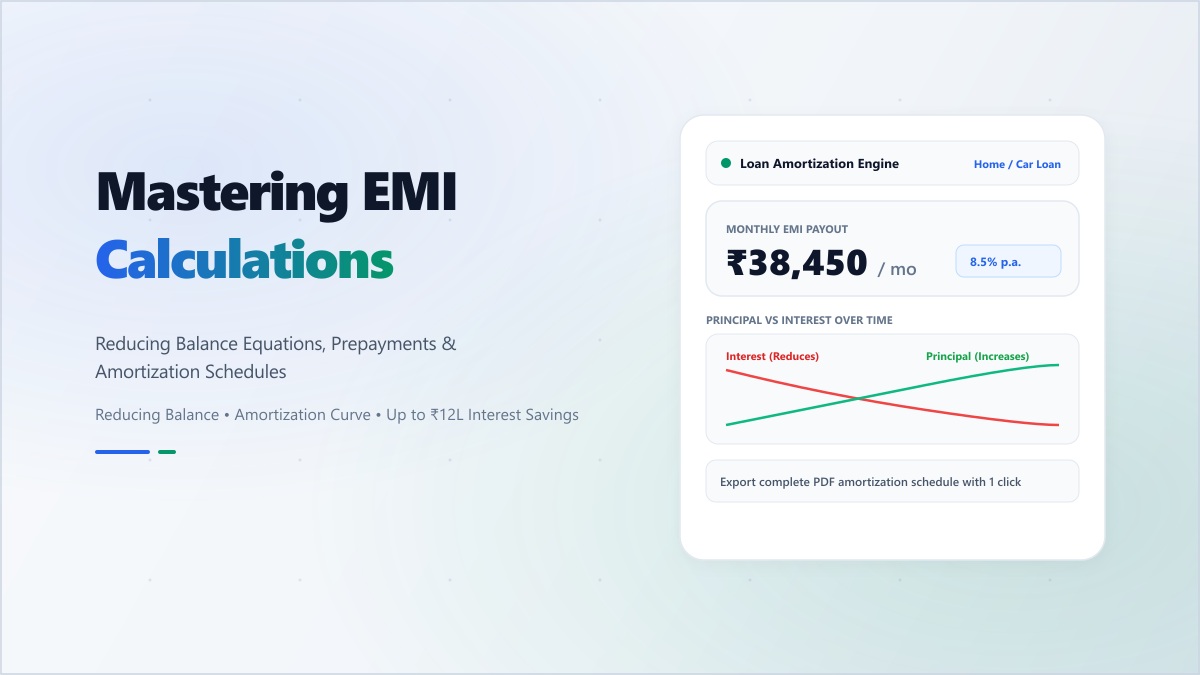
Most commercial banks use the Reducing Balance Method. Under this system, interest is recalculated every month strictly on the remaining principal balance. In the early months of a long-term home loan, up to 70%–80% of your EMI goes toward paying off interest! As you gradually pay down principal, the interest chunk shrinks and your principal repayment accelerates.
You can visualize this month-by-month trajectory instantly using our free Digibee EMI Calculator, which generates a complete amortization schedule and pie chart.
3 Strategies to Cut Your Loan Burden
- Make Prepayments Early: Paying just one extra EMI per year or contributing a small lump-sum bonus toward the principal during the first 3–5 years can wipe out 3 to 5 years from a 20-year mortgage.
- Choose the Shortest Affordable Tenure: A 30-year loan has slightly lower monthly EMIs than a 20-year loan, but you end up paying more than double the original loan amount in interest alone. Aim for 15 to 20 years if your income allows.
- Reinvest Savings into SIPs: Pair your debt management with wealth creation. Use our SIP Calculator to invest surplus funds in high-return index funds alongside your loan repayment.
"Financial freedom starts with knowing the math behind your commitments. Never sign a loan agreement without running the numbers yourself."
Take charge of your finances today. Run your numbers in the Digibee EMI Calculator to find your optimal monthly budget.